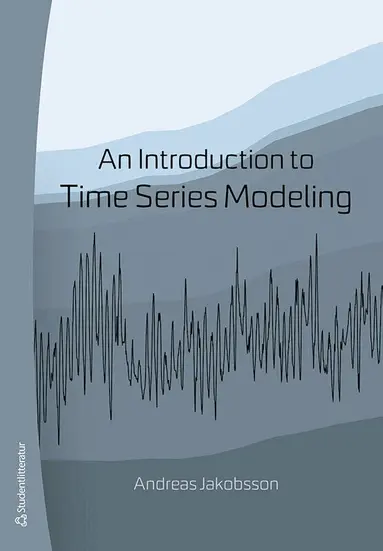
An introduction to time series modeling
- Vikt 0,55 kg
Bra pris nuLägsta priset på 1 månad
430 krhos Bokus · exkl. frakt
129 kr skillnad mellan billigaste och dyraste butik i lager
Dubbelkollade priser
Jämför 3 butiker
- Bokus, 430 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 06:51
430 kr
Lägst
- Akademibokhandeln, 559 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 06:53
559 kr
- Adlibris, 430 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
Slut i lagerFrakt: se butikenDubbelkollad 27 okt. 09:10
430 kr

Priser från butikernas flöden kan ha ändrats: det är priset hos butiken som gäller, så kontrollera det innan du handlar.
Prishistorik
Köp nu eller vänta?
Just nu kostar produkten 430 kr — det lägsta vi sett på 1 månad.
Under den tiden har det oftast legat runt 430–490 kr.
Pris idag
430 kr
- Lägst
- 430 kr
- Snitt
- 448 kr
- Högst
- 488 kr
| 2026-09-15 | 430 kr · Lägst hos Bokus |
|---|---|
| 2026-09-28 | 430 kr · Lägst hos Adlibris |
| 2026-09-29 | 430 kr · Lägst hos Bokus |
| 2026-10-10 | 488 kr · Lägst hos Bokus |
| 2026-10-18 | 430 kr · Lägst hos Bokus |
| 2026-10-24 | 488 kr · Lägst hos Bokus |
| 2026-10-31 | 430 kr · Lägst hos Bokus |
Om produkten
An introduction to time series modeling
Läs merLäs mindre
Time series analysis concerns the mathematical modeling of time varying phenomena, e.g., ocean waves, water levels in lakes and rivers, demand for electrical power, radar signals, muscular reactions, ECG-signals, or option prices at the stock market. This book gives a comprehensive presentation of stochastic models and methods in time series analysis.The book treats stochastic vectors and both univariate and multivariate stochastic processes, as well as how these can be used to identify suitable models for various forms of observations. Furthermore, different approaches such as least squares, the prediction error method, and maximum likelihood are treated in detail, together with results on the Cramér-Rao lower bound, dictating the theoretically possible estimation accuracy. Residual analysis and prediction of stochastic models are also treated, as well as how one may form time-varying models, including the recursive least squares and the Kalman filter. The book discusses how to implement the various methods using Matlab, and several Matlab functions and data sets are provided with the book. The book is aimed at advanced undergraduate and junior graduate students in statistics, mathematics, or engineering. Helpful prerequisites include courses in multivariate analysis, linear systems, basic probability, and stochastic processes.
Specifikationer
Fakta
- Vikt
- 0,55 kg
- GTIN
- 09789144158945
Uppgifter från tillverkare och butiker.