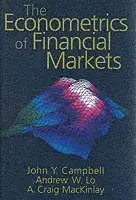
Econometrics of Financial Markets
- Vikt 1 kg
Bra pris nuLägsta priset på 1 månad
779 kr814 kr−4% senaste veckanhos Buyersclub · exkl. frakt
Jämfört med det lägsta pris vi sett de 30 dagarna före sänkningen.
120 kr skillnad mellan billigaste och dyraste butik i lager
Dubbelkollade priser
Jämför 5 butiker
- Buyersclub, 779 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerKampanjFrakt: se butikenDubbelkollad 05:34
779 kr
Lägst
- Bokus, 819 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 08:51
819 kr
- Akademibokhandeln, 899 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 08:53
899 kr
- Storytel Books, 899 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
Slut i lagerFrakt: se butikenDubbelkollad 09:08
899 kr
- Adlibris, 923 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
Slut i lagerFrakt: se butikenDubbelkollad 27 okt. 09:10
923 kr

Priser från butikernas flöden kan ha ändrats: det är priset hos butiken som gäller, så kontrollera det innan du handlar.
Prishistorik
Köp nu eller vänta?
Just nu kostar produkten 779 kr — det lägsta vi sett på 1 månad.
Under den tiden har det oftast legat runt 820 kr.
Pris idag
779 kr
- Lägst
- 779 kr
- Snitt
- 816 kr
- Högst
- 829 kr
| 2026-09-15 | 814 kr · Lägst hos Bokus |
|---|---|
| 2026-09-17 | 819 kr · Lägst hos Bokus |
| 2026-09-19 | 818 kr · Lägst hos Bokus |
| 2026-09-20 | 816 kr · Lägst hos Bokus |
| 2026-09-25 | 815 kr · Lägst hos Bokus |
| 2026-09-27 | 814 kr · Lägst hos Bokus |
| 2026-09-30 | 816 kr · Lägst hos Bokus |
| 2026-10-02 | 821 kr · Lägst hos Bokus |
| 2026-10-03 | 822 kr · Lägst hos Bokus |
| 2026-10-04 | 825 kr · Lägst hos Bokus |
| 2026-10-07 | 826 kr · Lägst hos Bokus |
| 2026-10-09 | 824 kr · Lägst hos Bokus |
| 2026-10-12 | 829 kr · Lägst hos Buyersclub |
| 2026-10-13 | 820 kr · Lägst hos Bokus |
| 2026-10-16 | 823 kr · Lägst hos Bokus |
| 2026-10-17 | 822 kr · Lägst hos Bokus |
| 2026-10-22 | 820 kr · Lägst hos Bokus |
| 2026-10-24 | 823 kr · Lägst hos Bokus |
| 2026-10-27 | 825 kr · Lägst hos Bokus |
| 2026-10-28 | 779 kr · Lägst hos Buyersclub |
Om produkten
Econometrics of Financial Markets
Läs merLäs mindre
The past twenty years have seen an extraordinary growth in the use of quantitative methods in financial markets. Finance professionals now routinely use sophisticated statistical techniques in portfolio management, proprietary trading, risk management, financial consulting, and securities regulation. This graduate-level textbook is intended for PhD students, advanced MBA students, and industry professionals interested in the econometrics of financial modeling. The book covers the entire spectrum of empirical finance, including: the predictability of asset returns, tests of the Random Walk Hypothesis, the microstructure of securities markets, event analysis, the Capital Asset Pricing Model and the Arbitrage Pricing Theory, the term structure of interest rates, dynamic models of economic equilibrium, and nonlinear financial models such as ARCH, neural networks, statistical fractals, and chaos theory. Each chapter develops statistical techniques within the context of a particular financial application. This exciting new text contains a unique and accessible combination of theory and practice, bringing state-of-the-art statistical techniques to the forefront of financial applications.Each chapter also includes a discussion of recent empirical evidence, for example, the rejection of the Random Walk Hypothesis, as well as problems designed to help readers incorporate what they have read into their own applications
Specifikationer
Fakta
- Vikt
- 1 kg
- GTIN
- 09780691043012
Uppgifter från tillverkare och butiker.