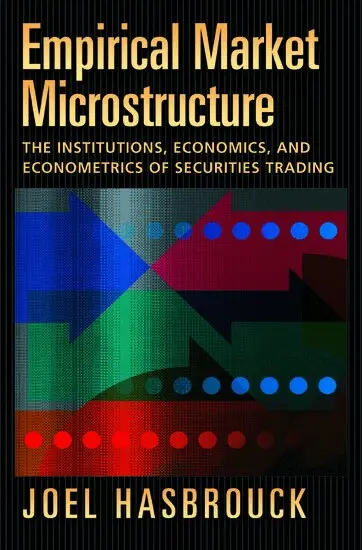
Empirical Market Microstructure
- Vikt 0,45 kg
1 696 krhos Bokus · exkl. frakt
513 kr skillnad mellan billigaste och dyraste butik i lager
Dubbelkollade priser
Jämför 3 butiker
- Bokus, 1 696 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 06:51
1 696 kr
Lägst
- Akademibokhandeln, 2 209 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 06:53
2 209 kr
- Adlibris, 1 244 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
Slut i lagerFrakt: se butikenDubbelkollad 27 okt. 09:10
1 244 kr

Priser från butikernas flöden kan ha ändrats: det är priset hos butiken som gäller, så kontrollera det innan du handlar.
Prishistorik
Köp nu eller vänta?
Just nu kostar produkten 1 696 kr — 468 kr över det lägsta vi sett på 1 månad.
Under den tiden har det oftast legat runt 1 240–1 700 kr.
Pris idag
1 696 kr
- Lägst
- 1 228 kr
- Snitt
- 1 496 kr
- Högst
- 1 696 kr
| 2026-09-15 | 1 228 kr · Lägst hos Adlibris |
|---|---|
| 2026-09-16 | 1 244 kr · Lägst hos Adlibris |
| 2026-10-03 | 1 659 kr · Lägst hos Bokus |
| 2026-10-05 | 1 244 kr · Lägst hos Adlibris |
| 2026-10-08 | 1 696 kr · Lägst hos Bokus |
Om produkten
Empirical Market Microstructure
Läs merLäs mindre
The interactions that occur in securities markets are among the fastest, most information-intensive, and most highly strategic of all economic phenomena. Empirical Market Microstructure is about the institutions that have evolved to handle our trading needs, the economic forces that guide our strategies, and statistical methods of using and interpreting the vast amount of information that these markets produce.The empirical methodsdiscussed in the book draw on the power of multivariate linear time series analysis. The book discusses the application of univariate ARMA analysis to trade prices, vector autoregressions to price and orderdata, and vector error correction models to situations where the same security is traded in many markets. In these models, the tools of random-walk decomposition and co-integration emerge as important to specification and interpretation.The statistical specifications dont simply arise, however, as progressively more refined descriptive models; they have strong economic underpinnings arising from asymmetric information, inventory control, and the strategies of theirparticipants. These topics are discusssed, interleaving with and emphasizing the connection to the statistical models.From a practical viewpoint, many of these models will beestimated to calibrate real-world trading strategies. Some market participants will be trying to discern strategies that generate profits from short-term trading. A much greater number, though, will be trying to accomplish trades that help diversify, hedge or reallocate a portfolio. Trading is not, for these agents, their primary economic purpose. They are simply trying to satisfy their trading needs at a minimal cost. The final part of the book discusses how these costs are measured, andstrategies to minimize them--both by splitting orders over time, and by the judicious use of limit orders.The book includes numerous exercises; solutions and other supportingmaterials are available on the author's web site.
Specifikationer
Fakta
- Vikt
- 0,45 kg
- GTIN
- 09780195301649
Uppgifter från tillverkare och butiker.