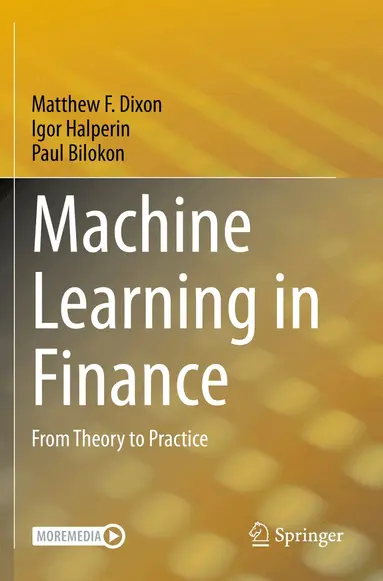
Machine Learning in Finance
- Vikt 0,79 kg
Bra pris nuLägsta priset på 1 månad
869 kr873 kr−0% senaste veckanhos Bokus · exkl. frakt
Jämfört med det lägsta pris vi sett de 30 dagarna före sänkningen.
260 kr skillnad mellan billigaste och dyraste butik i lager
Dubbelkollade priser
Jämför 3 butiker
- Bokus, 869 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 04:51
869 kr
Lägst
- Akademibokhandeln, 1 129 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 04:53
1 129 kr
- Adlibris, 923 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
Slut i lagerFrakt: se butikenDubbelkollad 27 okt. 09:10
923 kr

Priser från butikernas flöden kan ha ändrats: det är priset hos butiken som gäller, så kontrollera det innan du handlar.
Prishistorik
Köp nu eller vänta?
Just nu kostar produkten 869 kr — det lägsta vi sett på 1 månad.
Under den tiden har det oftast legat runt 880–890 kr.
Pris idag
869 kr
- Lägst
- 869 kr
- Snitt
- 882 kr
- Högst
- 896 kr
| 2026-09-15 | 896 kr · Lägst hos Bokus |
|---|---|
| 2026-09-17 | 886 kr · Lägst hos Bokus |
| 2026-09-18 | 885 kr · Lägst hos Bokus |
| 2026-09-23 | 886 kr · Lägst hos Bokus |
| 2026-09-25 | 883 kr · Lägst hos Bokus |
| 2026-09-27 | 884 kr · Lägst hos Bokus |
| 2026-09-30 | 886 kr · Lägst hos Bokus |
| 2026-10-02 | 889 kr · Lägst hos Bokus |
| 2026-10-04 | 890 kr · Lägst hos Bokus |
| 2026-10-07 | 887 kr · Lägst hos Bokus |
| 2026-10-09 | 883 kr · Lägst hos Bokus |
| 2026-10-12 | 880 kr · Lägst hos Bokus |
| 2026-10-13 | 878 kr · Lägst hos Bokus |
| 2026-10-16 | 880 kr · Lägst hos Bokus |
| 2026-10-17 | 877 kr · Lägst hos Bokus |
| 2026-10-19 | 878 kr · Lägst hos Bokus |
| 2026-10-20 | 876 kr · Lägst hos Bokus |
| 2026-10-22 | 873 kr · Lägst hos Bokus |
| 2026-10-24 | 876 kr · Lägst hos Bokus |
| 2026-10-27 | 877 kr · Lägst hos Bokus |
| 2026-11-01 | 869 kr · Lägst hos Bokus |
Om produkten
This book introduces machine learning methods in finance
Läs merLäs mindre
It presents a unified treatment of machine learning and various statistical and computational disciplines in quantitative finance, such as financial econometrics and discrete time stochastic control, with an emphasis on how theory and hypothesis tests inform the choice of algorithm for financial data modeling and decision making. With the trend towards increasing computational resources and larger datasets, machine learning has grown into an important skillset for the finance industry. This book is written for advanced graduate students and academics in financial econometrics, mathematical finance and applied statistics, in addition to quants and data scientists in the field of quantitative finance.Machine Learning in Finance: From Theory to Practice is divided into three parts, each part covering theory and applications. The first presents supervised learning for cross-sectional data from both a Bayesianand frequentist perspective. The more advanced material places a firm emphasis on neural networks, including deep learning, as well as Gaussian processes, with examples in investment management and derivative modeling. The second part presents supervised learning for time series data, arguably the most common data type used in finance with examples in trading, stochastic volatility and fixed income modeling. Finally, the third part presents reinforcement learning and its applications in trading, investment and wealth management. Python code examples are provided to support the readers' understanding of the methodologies and applications. The book also includes more than 80 mathematical and programming exercises, with worked solutions available to instructors. As a bridge to research in this emergent field, the final chapter presents the frontiers of machine learning in finance from a researcher's perspective, highlighting how many well-known concepts in statistical physics are likelyto emerge as important methodologies for machine learning in finance.
Specifikationer
Fakta
- Vikt
- 0,79 kg
- GTIN
- 09783030410704
Uppgifter från tillverkare och butiker.