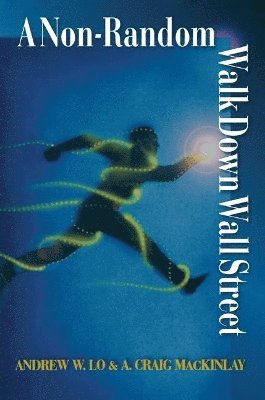
Non-Random Walk Down Wall Street
- Vikt 0,65 kg
519 krhos Bokus · exkl. frakt
150 kr skillnad mellan billigaste och dyraste butik i lager
Dubbelkollat idag
Jämför 2 butiker
- Bokus, 519 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 02:51
519 kr
Lägst
- Akademibokhandeln, 669 kr, frakt enligt butiken. Till butik (öppnas i ny flik)
I lagerFrakt: se butikenDubbelkollad 01:53
669 kr
Priser från butikernas flöden kan ha ändrats: det är priset hos butiken som gäller, så kontrollera det innan du handlar.
Prishistorik
Köp nu eller vänta?
Just nu kostar produkten 519 kr — 11 kr över det lägsta vi sett på 4 veckor.
Under den tiden har det oftast legat runt 510–520 kr.
Pris idag
519 kr
- Lägst
- 508 kr
- Snitt
- 521 kr
- Högst
- 659 kr
| 2026-09-18 | 659 kr · Lägst hos Akademibokhandeln |
|---|---|
| 2026-09-19 | 508 kr · Lägst hos Bokus |
| 2026-09-21 | 510 kr · Lägst hos Bokus |
| 2026-09-27 | 513 kr · Lägst hos Bokus |
| 2026-09-28 | 515 kr · Lägst hos Bokus |
| 2026-09-29 | 514 kr · Lägst hos Bokus |
| 2026-10-02 | 517 kr · Lägst hos Bokus |
| 2026-10-03 | 518 kr · Lägst hos Bokus |
| 2026-10-04 | 519 kr · Lägst hos Bokus |
| 2026-10-05 | 521 kr · Lägst hos Bokus |
| 2026-10-07 | 523 kr · Lägst hos Bokus |
| 2026-10-09 | 519 kr · Lägst hos Bokus |
| 2026-10-12 | 520 kr · Lägst hos Bokus |
| 2026-10-13 | 518 kr · Lägst hos Bokus |
| 2026-10-16 | 519 kr · Lägst hos Bokus |
Om produkten
Non-Random Walk Down Wall Street
Läs merLäs mindre
For over half a century, financial experts have regarded the movements of markets as a random walk--unpredictable meanderings akin to a drunkard's unsteady gait--and this hypothesis has become a cornerstone of modern financial economics and many investment strategies. Here Andrew W. Lo and A. Craig MacKinlay put the Random Walk Hypothesis to the test. In this volume, which elegantly integrates their most important articles, Lo and MacKinlay find that markets are not completely random after all, and that predictable components do exist in recent stock and bond returns. Their book provides a state-of-the-art account of the techniques for detecting predictabilities and evaluating their statistical and economic significance, and offers a tantalizing glimpse into the financial technologies of the future. The articles track the exciting course of Lo and MacKinlay's research on the predictability of stock prices from their early work on rejecting random walks in short-horizon returns to their analysis of long-term memory in stock market prices.A particular highlight is their now-famous inquiry into the pitfalls of "data-snooping biases" that have arisen from the widespread use of the same historical databases for discovering anomalies and developing seemingly profitable investment strategies. This book invites scholars to reconsider the Random Walk Hypothesis, and, by carefully documenting the presence of predictable components in the stock market, also directs investment professionals toward superior long-term investment returns through disciplined active investment management.
Specifikationer
Fakta
- Vikt
- 0,65 kg
- GTIN
- 09780691092560
Uppgifter från tillverkare och butiker.